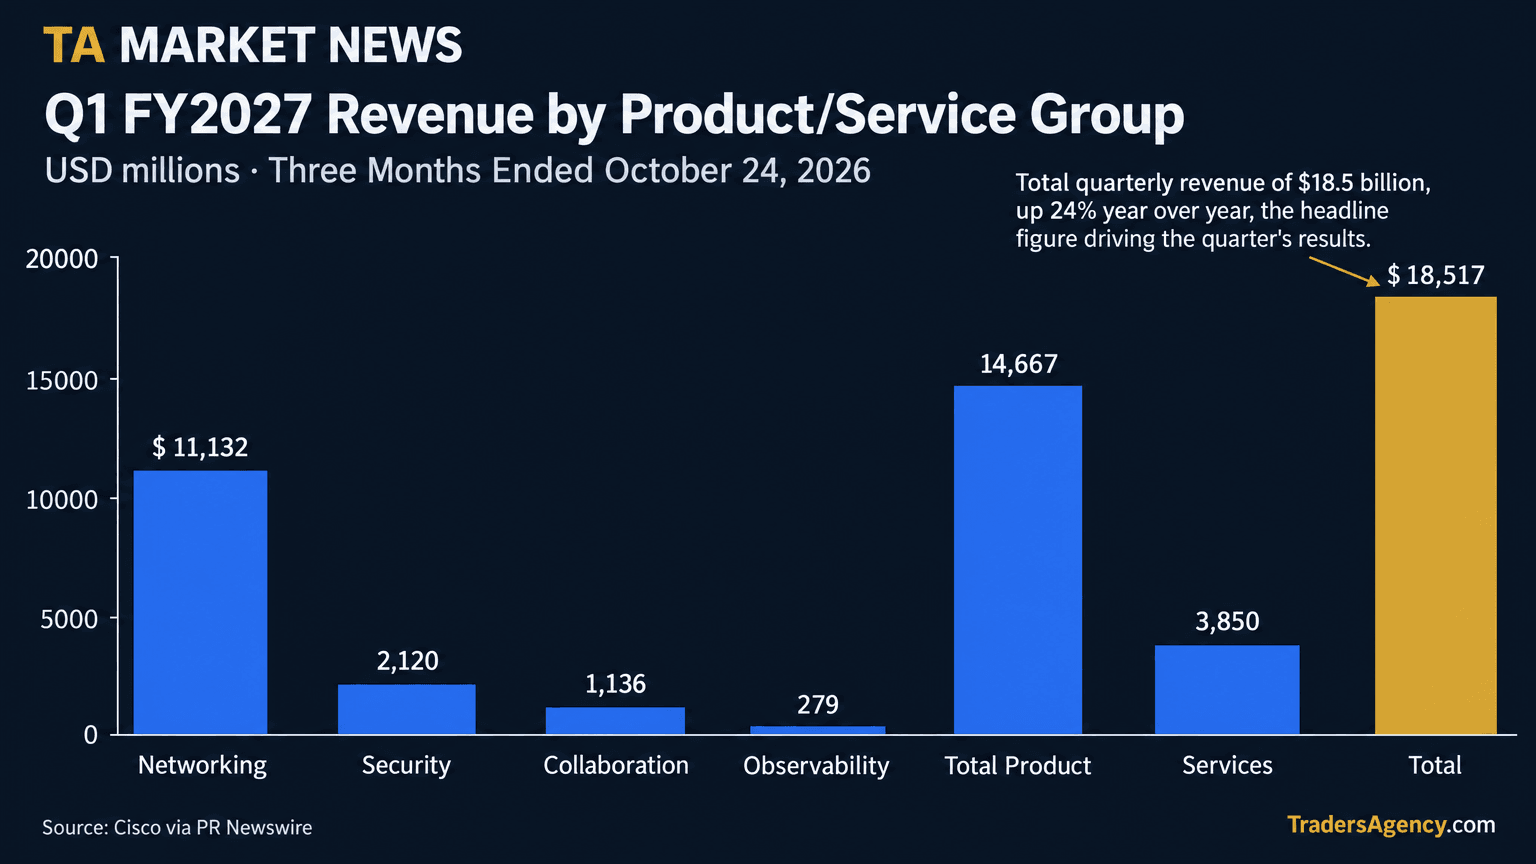
Cisco reported fiscal first-quarter revenue of $18.5 billion, up 24% from $14.9 billion a year earlier, and raised its full-year fiscal 2027 outlook after results came in above the high end of its own guidance ranges, according to the company's earnings release distributed via PR Newswire and reported by CNBC.
A Record Quarter on Paper
GAAP net income rose to $4.6 billion, or $1.14 per diluted share, from $2.9 billion, or $0.72 per share, a year earlier, a 59% increase in net income and a 58% rise in EPS, Cisco said in its earnings release. On a non-GAAP basis, net income climbed 39% to $5.6 billion, or $1.40 per share, up from $4.0 billion, or $1.00 per share, in the prior-year quarter.
By product line, Cisco's networking segment generated $11.1 billion in revenue, the largest single contributor to the quarter, followed by services at $3.85 billion, security at $2.12 billion, collaboration at $1.14 billion and observability at $279 million, according to the figures disclosed in the earnings release.
Cisco's chief financial officer, Mark Patterson, said in the release that "Q1 FY27 was another record quarter for Cisco, with revenue, non-GAAP operating margin, and non-GAAP EPS all exceeding the high end of our guidance ranges." Patterson also attributed the gap between earnings growth and revenue growth to operating leverage, saying that "as our business continues to scale, we are unlocking significant operating leverage which is enabling us to grow earnings much faster than revenue."
Margins Moved in Different Directions
The quarter's profitability picture was mixed beneath the headline beat. GAAP operating income rose 66% to $5.6 billion, lifting GAAP operating margin to 30.2%, while non-GAAP operating income grew 37% to $7.0 billion, putting non-GAAP operating margin at 37.8%, per the earnings release.
At the same time, GAAP gross margin compressed. Total GAAP gross margin fell to 63.7% from 65.5% a year earlier, a decline of 1.8 percentage points based on the two reported figures (our calculation: 65.5% minus 63.7%). Product gross margin dropped more sharply, to 61.8% from 64.5%, while services gross margin improved to 70.9% from 68.4%, according to the release. Cisco's tax position also shifted: the GAAP effective tax rate rose to 17.2% from 15.7%, while the non-GAAP effective tax rate eased slightly to 18.5% from 19.0%.
Cisco's summary language described the quarter as delivering a "record non-GAAP operating margin, reflecting focused execution and operating efficiency," alongside "broad-based high demand for Cisco technology with double-digit growth across all geographies and customer markets," the company said in its release.
Raised Full-Year Guidance
Cisco lifted its fiscal 2027 outlook, now projecting full-year revenue of $74.8 billion to $75.8 billion and non-GAAP EPS of $5.47 to $5.53, according to the earnings release. For the fiscal second quarter, the company guided to revenue of $18.0 billion to $18.2 billion and adjusted EPS of $1.34 to $1.36.
CNBC reported that Cisco's second-quarter revenue guidance topped the average analyst estimate of $17.88 billion, according to LSEG data cited by the outlet, and that the adjusted EPS guidance beat the average analyst estimate of $1.23. CNBC also reported that Cisco's stock price was up about 35% so far this year as of Thursday's close, outperforming the Nasdaq's 9% gain over the same period.
AI Infrastructure and a "Networking Supercycle"
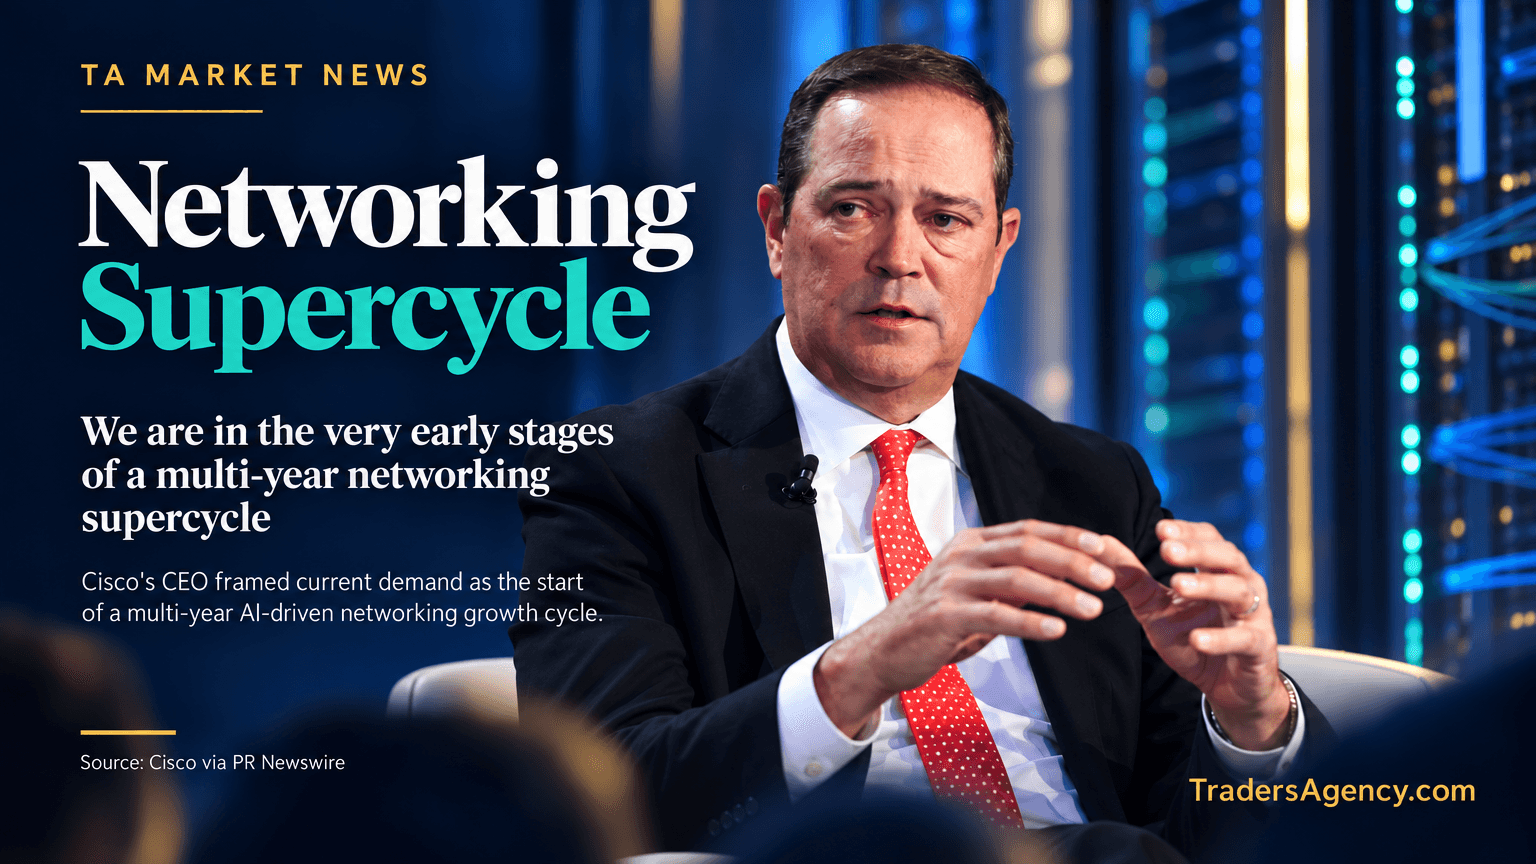
Cisco's chief executive framed the results within a broader narrative about artificial intelligence demand, saying in the earnings release that "organizations are turning to Cisco for our trusted, market-defining technology and our expertise to help them scale, secure and optimize their environments for the agentic AI era." The CEO added that the company is "in the very early stages of a multi-year networking supercycle" and expressed confidence in capturing what was described as a multi-billion-dollar opportunity.
CNBC reported that Cisco has been trying to establish a stronger position in the AI infrastructure buildout after missing out on the early years of the generative AI boom, framing the current results as part of that broader push.
Cisco's own forward-looking disclosures flagged risk alongside opportunity. The company's earnings release identified "spending levels of cloud and hyperscaler customers and the timing and scale of AI infrastructure deployments" and "large and concentrated purchases of AI infrastructure solutions by cloud and hyperscaler customers" as factors that could affect future results, underscoring that a meaningful share of the networking supercycle narrative depends on a relatively small number of large customers continuing to spend at scale.
Reading the Results
Taken together, the reported figures point to a quarter in which top-line growth, record non-GAAP operating margin, and raised guidance all moved in the same direction, which is consistent with Cisco's own characterization of broad-based demand. At the same time, the divergence between a rising non-GAAP operating margin and a declining GAAP gross margin is notable: product gross margin fell to 61.8% from 64.5% while services gross margin rose to 70.9% from 68.4%, and product revenue grew 32% year over year compared with 1% growth in services, according to the earnings release. One interpretation of those figures — an analytical reading rather than a company statement — is that the gross margin pressure is concentrated on the product side, where revenue grew fastest, while operating expenses scaled more slowly than revenue. The release did not detail the specific drivers of the gross margin decline beyond the reported percentages.
The explicit risk language around hyperscaler concentration is also worth weighing against the bullish framing of a multi-year supercycle. Cisco itself disclosed that its results could be sensitive to the timing and scale of a relatively small set of large AI infrastructure customers, which is a qualification investors may want to keep in view alongside the raised guidance.
Bottom Line
Cisco's fiscal first-quarter results exceeded the company's own guidance across revenue, non-GAAP operating margin, and non-GAAP EPS, prompting a raise to full-year fiscal 2027 revenue and EPS targets. The quarter showed strength in networking revenue and non-GAAP profitability, tempered by a year-over-year decline in GAAP gross margin and company-disclosed risk tied to concentrated hyperscaler AI infrastructure spending. Guidance for the next quarter exceeded average analyst estimates reported by CNBC, and the stock has meaningfully outperformed the Nasdaq this year, though Cisco's own forward-looking statements caution that future results remain sensitive to the pace and scale of AI infrastructure deployment among a limited number of large customers.
DISCLAIMER: Traders Agency does not offer financial advice. The information provided is for educational purposes only and should not be considered financial advice. Traders Agency is not responsible for any financial losses or consequences resulting from the use of the information provided. Trading carries inherent risks and may not be suitable for all individuals. You are advised to conduct your own research and seek personalized advice before making any investment decisions, recognizing the potential risks and rewards involved.
- CNBC Top News: Cisco (CSCO) Q1 2027 earnings · accessed Nov 12, 2026
- Cisco via PR Newswire: CISCO REPORTS FIRST QUARTER EARNINGS · accessed Nov 12, 2026
See more from Traders Agency on Google
Make us a preferred source and our market analysis will appear more prominently in your Google Search, Top Stories, and AI results.
Add to Preferred Sources