Ross Stores topped its own third-quarter earnings guidance and raised its full-year profit outlook in results released November 19, but the stock fell about 3% as investors focused on a fourth-quarter forecast that came in below Wall Street's expectations, CNBC reported.
Third-Quarter Results Top Guidance
Ross Stores reported third-quarter fiscal 2026 sales up 12% to $6.3 billion, compared with $5.6 billion a year earlier, according to the company's earnings release filed with the SEC. Comparable store sales rose 8%, which the company said was primarily driven by customer traffic.
Diluted earnings per share came in at $1.91, above the company's own guidance range of $1.75 to $1.83. Net earnings were $606 million, up from $512 million in the same quarter last year. Operating margin was 12.3%, up 70 basis points year over year and above the company's planned range of 11.7% to 12.0%.
Chief Executive Jim Conroy said the company was "extremely pleased" with its third-quarter sales and earnings growth, "particularly given the more challenging comparisons" it faced versus the prior year, according to the earnings release.
Full-Year Outlook Raised
Based on the year-to-date results and updated fourth-quarter guidance, Ross Stores raised its full fiscal 2026 earnings-per-share projection to a range of $8.75 to $8.84, the company said in its release. For the fourth quarter specifically, the company maintained its prior outlook for comparable store sales growth of 4% to 5%, which it noted would be on top of last year's 9% gain, and projected EPS of $2.16 to $2.25, representing growth of 8% to 13%.
Why Shares Slid Despite the Beat
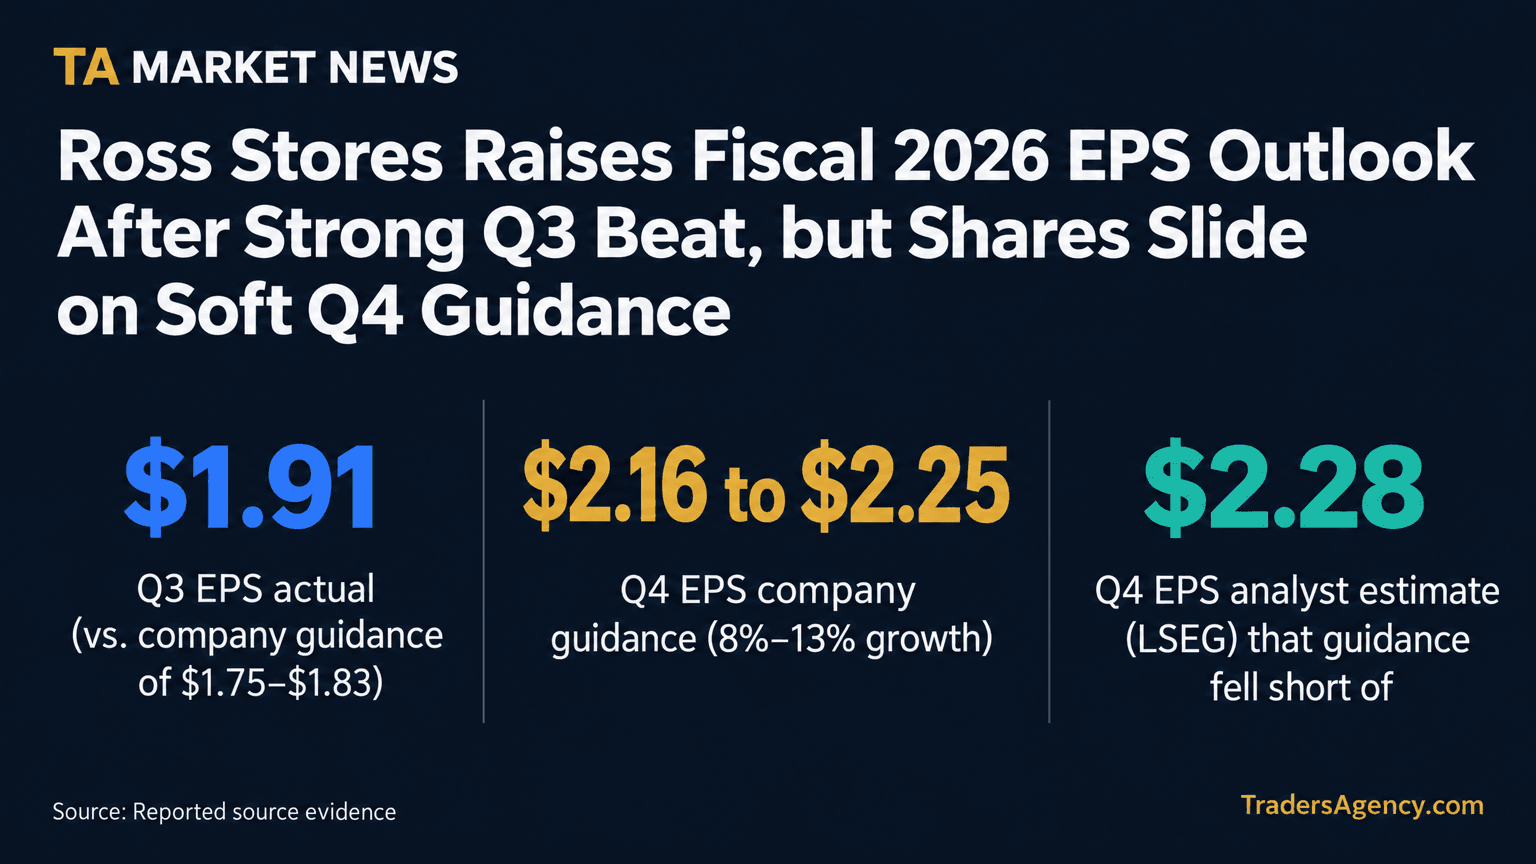
Even with the earnings beat and the raised annual outlook, Ross Stores shares fell about 3%, according to CNBC, which reported that the decline reflected disappointment with the company's forecast. CNBC noted that Ross's projected fourth-quarter EPS range of $2.16 to $2.25 fell short of the $2.28 per share that analysts polled by LSEG had expected, while the company's projected comparable sales growth of 4% to 5% came in below the 5.1% consensus tracked by StreetAccount.
In other words, the market's reaction centered not on the quarter that already happened, but on the guidance for the quarter ahead. A beat against the company's own prior guidance was not enough to offset a forward outlook that lagged sell-side expectations compiled by LSEG and StreetAccount, as reported by CNBC.
The Tariff Refund's Role in the Numbers
A notable factor in the year's earnings trajectory is a one-time item: approximately $253 million of IEEPA tariff refunds recognized in the second quarter, which the company said benefited earnings per share by approximately $0.60. Ross Stores said its full-year guidance includes this benefit, meaning the raised $8.75 to $8.84 EPS range is not purely a reflection of underlying operating momentum but also carries this earlier one-time boost.
Importantly, the company was explicit that the tariff refund was an earnings item, not a sales driver. It stated that customer traffic remained the primary driver of comparable store sales growth, separating the topline strength from the EPS tailwind created by the refund.
This distinction matters for assessing the sustainability of the comparable-sales trend. Based on the company's own characterization — an interpretation of its disclosures rather than a company forecast — the 8% comparable sales growth in the third quarter and the 4% to 5% comparable sales growth guided for the fourth quarter are tied to traffic trends rather than to the tariff refund, since the company described the refund as an earnings item and identified customer traffic as the primary driver of comp growth. If that attribution holds, the comparable-sales growth itself does not reflect the one-time refund, even though full-year EPS includes the approximate $0.60 benefit. One limitation for investors weighing the durability of the sales trend: the company did not provide guidance beyond fiscal 2026 or break down how much of the traffic gain stems from recurring versus non-recurring factors.
Store Growth, Buybacks and Dividend
Ross Stores also reported operational progress during the quarter. The company opened 51 new stores, including 41 Ross and 10 dd's DISCOUNTS locations, which completed its planned 115 new store openings for fiscal 2026.
On capital returns, Ross Stores repurchased 1.4 million shares for an aggregate $319 million during the third quarter under its two-year, $2.55 billion buyback authorization approved by its board in March 2026. The board also declared a regular quarterly cash dividend of $0.445 per share, payable December 31, 2026, to stockholders of record as of December 8, 2026.
Bottom Line
Ross Stores delivered a third quarter that exceeded its own prior guidance on earnings per share and operating margin, and the company responded by raising its full-year EPS outlook to $8.75-$8.84. Yet the stock declined about 3% because the fourth-quarter guidance, while still showing year-over-year growth, fell short of analyst expectations tracked by LSEG and StreetAccount, as reported by CNBC. The company's own disclosures indicate that comparable-sales growth has been driven primarily by customer traffic rather than by the one-time tariff refund, which benefited full-year EPS by roughly $0.60 — a distinction that may offer some reassurance about the quality of the sales trend even as the market digests a guidance range that undershot Wall Street's numbers.
DISCLAIMER: Traders Agency does not offer financial advice. The information provided is for educational purposes only and should not be considered financial advice. Traders Agency is not responsible for any financial losses or consequences resulting from the use of the information provided. Trading carries inherent risks and may not be suitable for all individuals. You are advised to conduct your own research and seek personalized advice before making any investment decisions, recognizing the potential risks and rewards involved.
- Ross Stores / SEC: Document · accessed Nov 20, 2026
- CNBC Top News: Stocks moving the most today: Live updates · accessed Nov 20, 2026
See more from Traders Agency on Google
Make us a preferred source and our market analysis will appear more prominently in your Google Search, Top Stories, and AI results.
Add to Preferred Sources