ServiceNow shares sank 25% on Thursday, heading for the worst day in the company's history, after third-quarter results underwhelmed Wall Street and reignited concerns that artificial intelligence could disrupt traditional enterprise software, according to CNBC. The selloff came even though the company slightly raised its full-year 2026 subscription revenue outlook to between $15.78 billion and $15.79 billion, CNBC reported.
What the Quarter Actually Showed
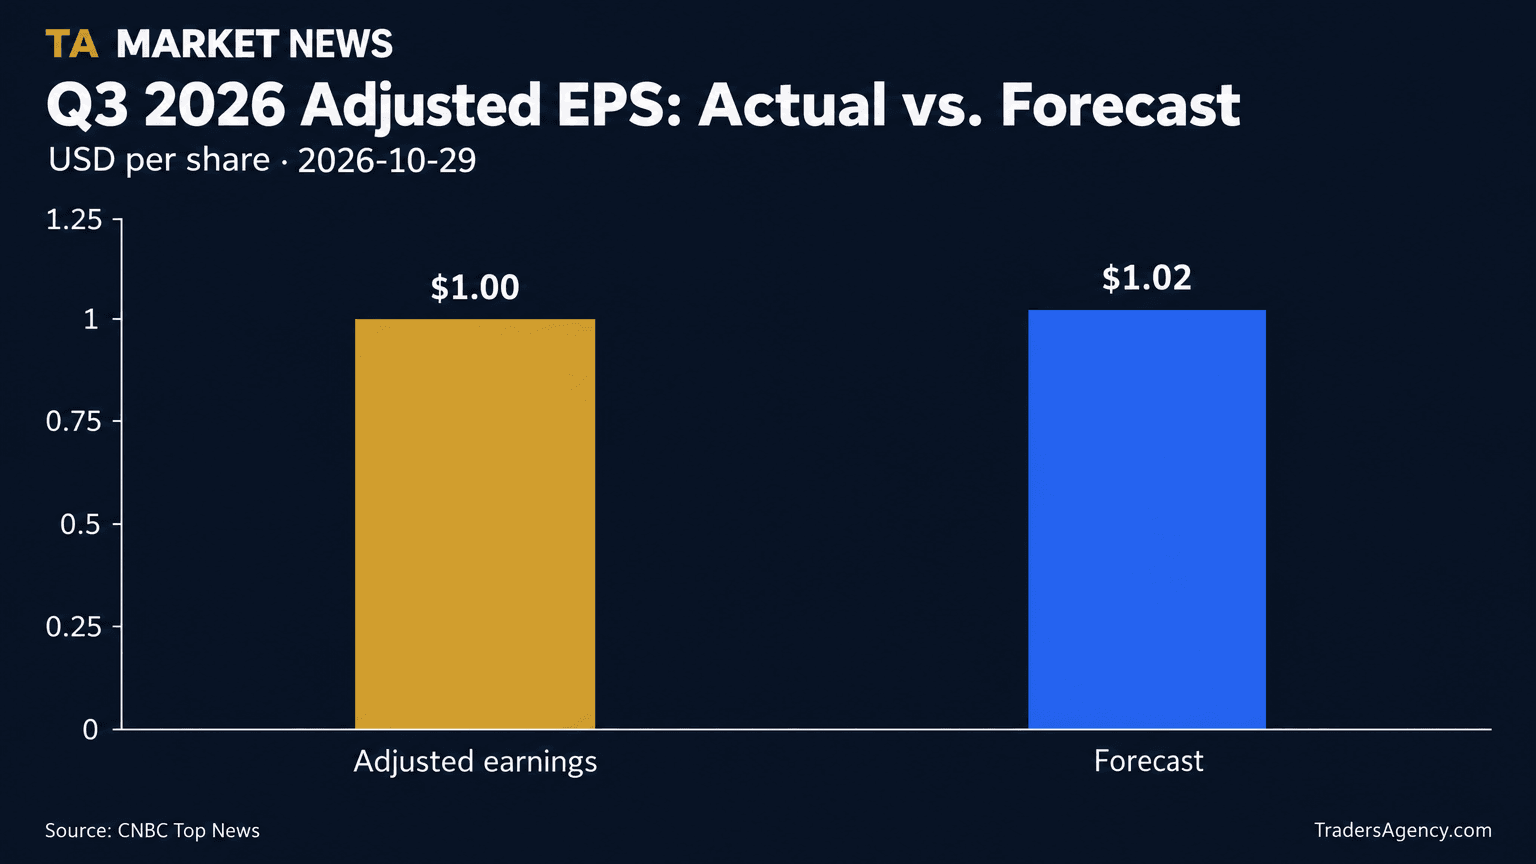
Third-quarter revenue grew more than 20% to $4.11 billion, roughly in line with a $4.10 billion analyst estimate compiled by LSEG, per CNBC. Adjusted earnings per share came in at $1.00, missing the $1.02 forecast cited by CNBC. By our calculation using the exact figures reported by CNBC, the $1.00 result was $0.02 below the $1.02 forecast, a shortfall of roughly 1.96% ((1 minus 1.02) divided by 1.02, multiplied by 100). That is a modest miss in isolation, underscoring that the scale of Thursday's stock reaction was not proportional to the earnings gap alone.
One bright spot CNBC highlighted was net new AI average contract value, which jumped 65% in the quarter. Separately, Seeking Alpha's market news desk reported that analysts covering the stock remained constructive overall, citing strong AI activity and underlying business momentum even as the shares sold off.
Why the Forecast Spooked Investors
Citi analyst Tyler Radke told CNBC the quarter was "a little bit uncharacteristic for ServiceNow standards, just in terms of the lack of upside." Read against the reported figures — revenue roughly in line with the LSEG consensus and adjusted EPS two cents short of the forecast cited by CNBC — that comment suggests the absence of a clear beat, rather than any single data point, unsettled investors already on edge about AI's long-term effect on software subscription models. That reading is interpretation of the attributed quote and reported numbers, not a claim made by the company.
Radke also pointed to a more specific concern, as reported by CNBC: the lack of immediate payoff from ServiceNow's newly formed forward-deployed engineering team, a group that embeds directly in enterprise clients to build AI solutions. According to Radke, the market wanted to see benefits from that investment sooner, and he suggested the real inflection point may not arrive until next year. That timing gap between investment and return appears central to why a quarter with record AI contract growth and a raised subscription forecast still triggered a historic drop.
Separately, Seeking Alpha's market news desk reported that analysts attribute much of the forecast weakness to timing, accounting, and changes in the scope of the cRPO, or current remaining performance obligations, metric, while still acknowledging investor concerns. That framing suggests at least part of what looked like a guidance miss may reflect reporting mechanics rather than a genuine deterioration in demand, though the distinction did little to calm the market in the immediate aftermath.
AI Disruption Fears Resurface
CNBC noted that the results did little to overturn recent "SaaSpocalypse" fears — concerns that new AI capabilities will upend traditional software business models — a backdrop the network cited alongside ServiceNow's quarterly report.
Bottom line: on the reporting from CNBC and Seeking Alpha, Thursday's 25% decline appears driven less by the headline numbers — revenue of $4.11 billion against a $4.10 billion LSEG estimate, adjusted EPS of $1.00 versus the $1.02 forecast, and a slightly raised full-year 2026 subscription revenue outlook of $15.78 billion to $15.79 billion — than by questions of timing. Those include when investments such as the forward-deployed engineering team will pay off and how much of the softer forecast reflects timing, accounting and cRPO scope changes rather than weaker demand, per the analysts cited by Seeking Alpha. Those analysts remained constructive, but as Radke told CNBC, the inflection investors want to see may not arrive until next year.
DISCLAIMER: Traders Agency does not offer financial advice. The information provided is for educational purposes only and should not be considered financial advice. Traders Agency is not responsible for any financial losses or consequences resulting from the use of the information provided. Trading carries inherent risks and may not be suitable for all individuals. You are advised to conduct your own research and seek personalized advice before making any investment decisions, recognizing the potential risks and rewards involved.
- Seeking Alpha Market News: ServiceNow crashes on weak forecast: What Wall Street's saying · accessed Oct 29, 2026
- CNBC Top News: ServiceNow (NOW) earnings Q3 2026 · accessed Oct 29, 2026
See more from Traders Agency on Google
Make us a preferred source and our market analysis will appear more prominently in your Google Search, Top Stories, and AI results.
Add to Preferred Sources