Taiwan Semiconductor Manufacturing Co. reported its sixth consecutive quarter of record profit, with results that beat both its own guidance and analyst estimates, and the chipmaker guided fourth-quarter revenue up roughly 14% from the third quarter as artificial-intelligence demand continues to outstrip its production capacity.
A Record Quarter, Again
TSMC reported a record third-quarter net profit of NT$763.06 billion, up 68.7% from a year earlier and ahead of the NT$746.3 billion analyst estimate, giving a net margin of 51.1%, according to AskTraders. Reuters, cited by Central Oregon Daily, described it as the company's highest-ever quarterly net income and its 11th straight quarter of profit growth.
Revenue of US$46.72 billion topped the company's own guidance range of US$44.6 billion to US$45.8 billion and the US$45.62 billion analyst consensus, AskTraders reported. In Taiwan dollar terms, revenue rose about 50%, AskTraders said, to NT$1.49 trillion, according to CNBC. Earnings came to US$4.60 per American depositary receipt, against an analyst average of US$4.45 and US$2.92 a year earlier, per AskTraders.
Margins Hold Firm, FX Assumption Set for Q4
Gross margin came in at 66.4%, inside the company's 65% to 67% guidance range but down from 67.7% in the second quarter and a touch below the 66.5% analysts had expected, AskTraders and TIKR both noted. Operating margin of 58.7% beat the 56.0% to 58.0% guidance range, which CNBC framed as evidence of pricing power as AI-driven chip demand holds firm.
For the fourth quarter, TSMC guided gross margin of 65.0% to 67.0% and operating margin of 56.5% to 58.5%, based on an exchange-rate assumption of NT$31.8 to the U.S. dollar, according to AskTraders. CFO Wendell Huang said on the earnings call, as reported by TIKR, that margin dilution from overseas fabs should run close to 2% this year and widen to 3% to 4% later as more U.S. fabs ramp up production.
HPC and Advanced Nodes Dominate the Mix
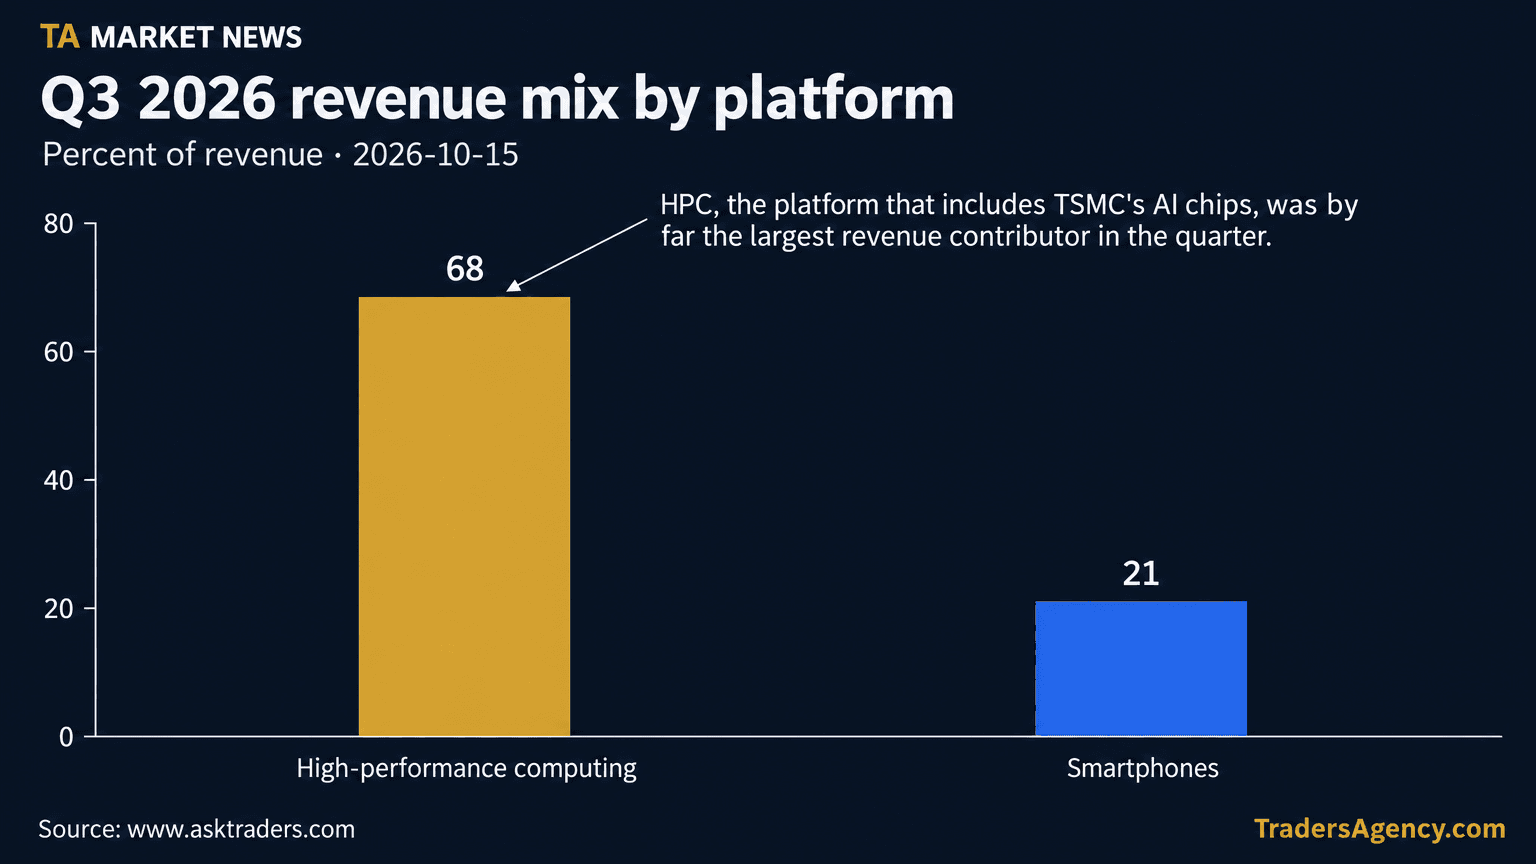
High-performance computing, the platform that includes TSMC's AI chips, accounted for 68% of third-quarter revenue, while smartphones made up 21%, according to CNBC and AskTraders. On those two reported figures, HPC's share of revenue was about 224% larger than the smartphone share ((68 − 21) ÷ 21 × 100 = 223.8%) — a calculation based on the reported mix, not a company disclosure. Automotive was the fastest-growing segment sequentially, up 23% quarter-on-quarter, CNBC reported.
By process node, the 3-nanometre process contributed 33% of wafer revenue and the newer 2-nanometre process 8%, per AskTraders. Advanced technologies, defined as 7-nanometre and more advanced, made up 79% of total wafer revenue, CNBC reported, with 3-nanometre chips the single largest contributor, followed by 5- and 7-nanometre chips. TSMC said fourth-quarter business would be supported by continued strong demand for advanced technologies, including the ramp-up of its 2-nanometre process, and pointed to the emergence of agentic AI processors and continued demand for networking chips as future drivers of silicon demand, per CNBC and Central Oregon Daily. Reuters, via Central Oregon Daily, separately reported that analysts say demand for TSMC's AI chipmaking capacity and its advanced packaging technology, CoWoS, remains strong.
Guidance Points to Acceleration, Management Signals Caution on 2027
TSMC guided fourth-quarter revenue to between US$52.3 billion and US$54.3 billion, representing roughly a 14% sequential increase and a 58% year-over-year jump at the midpoint, according to CNBC's account of the earnings call. Reuters, via Central Oregon Daily, put the potential year-over-year increase as high as 61%. CEO C.C. Wei raised the company's full-year 2026 revenue growth forecast to about 44% in U.S. dollar terms, up from a prior forecast of more than 40% given last quarter, TIKR and Central Oregon Daily reported. Read together, those guidance figures are an indication — an interpretation of the company's own outlook rather than a projection of results — that TSMC still sees acceleration ahead rather than a slowdown.
Even so, Wei struck a cautious note on the year ahead. "Looking ahead, we continue to observe consumer and price-sensitive end-markets segments are being challenged due to the impact of rising component prices and macroeconomic uncertainties," Wei said on the earnings call, as reported by Reuters via Central Oregon Daily, adding: "As such, we are being prudent in our business planning going into 2027." TSMC nonetheless maintained its 2026 capital spending plan at $60 billion to $64 billion and said capital expenditure from 2026 to 2028 would be significantly higher than in the previous three years, per Central Oregon Daily and CNBC. Gary Tan, portfolio manager at Allspring Global Investments, which owns TSMC stock, said in comments reported by Reuters via Central Oregon Daily: "The key risk is that TSMC's caution translates into broader earnings downgrades across a value chain accustomed to sustained upward revisions, but for now, this looks like sensible expectation management rather than a change in the sector's long-term fundamentals." The bottom line: record results, a raised full-year growth forecast and unchanged heavy capital spending sit alongside management's explicit prudence on 2027 — an interpretation of the attributed figures and quotes above, not a forecast of future results.
DISCLAIMER: Traders Agency does not offer financial advice. The information provided is for educational purposes only and should not be considered financial advice. Traders Agency is not responsible for any financial losses or consequences resulting from the use of the information provided. Trading carries inherent risks and may not be suitable for all individuals. You are advised to conduct your own research and seek personalized advice before making any investment decisions, recognizing the potential risks and rewards involved.
- CNBC Top News: TSMC posts record profit for a sixth straight quarter, beating estimates on AI boom · accessed Oct 15, 2026
- www.tikr.com: TSMC Posts a Sixth Straight Record Quarter, and Its Q4 Guide Says the AI Boom Isn’t Slowing. Here’s the Fuller Picture · accessed Oct 15, 2026
- finance.yahoo.com: TSMC lifts revenue forecast, pledges more capital spending to meet AI chip demand · accessed Oct 15, 2026
- www.centraloregondaily.com: TSMC 'prudent' going into 2027 after posting sixth straight quarter of record profit · accessed Oct 15, 2026
- www.asktraders.com: TSMC Posts Record Profit and Beats Guidance as Chip Rout Hits Shares · accessed Oct 15, 2026
See more from Traders Agency on Google
Make us a preferred source and our market analysis will appear more prominently in your Google Search, Top Stories, and AI results.
Add to Preferred Sources